We use cookies to make your experience better.
To comply with the new e-Privacy directive, you agree to the privacy policy and our use of cookies

Best Card Payment Machines for UK Retail Shops: How to Choose the Right One
Card Payment Machines for UK Retail: Everything Shop Owners Need to Know
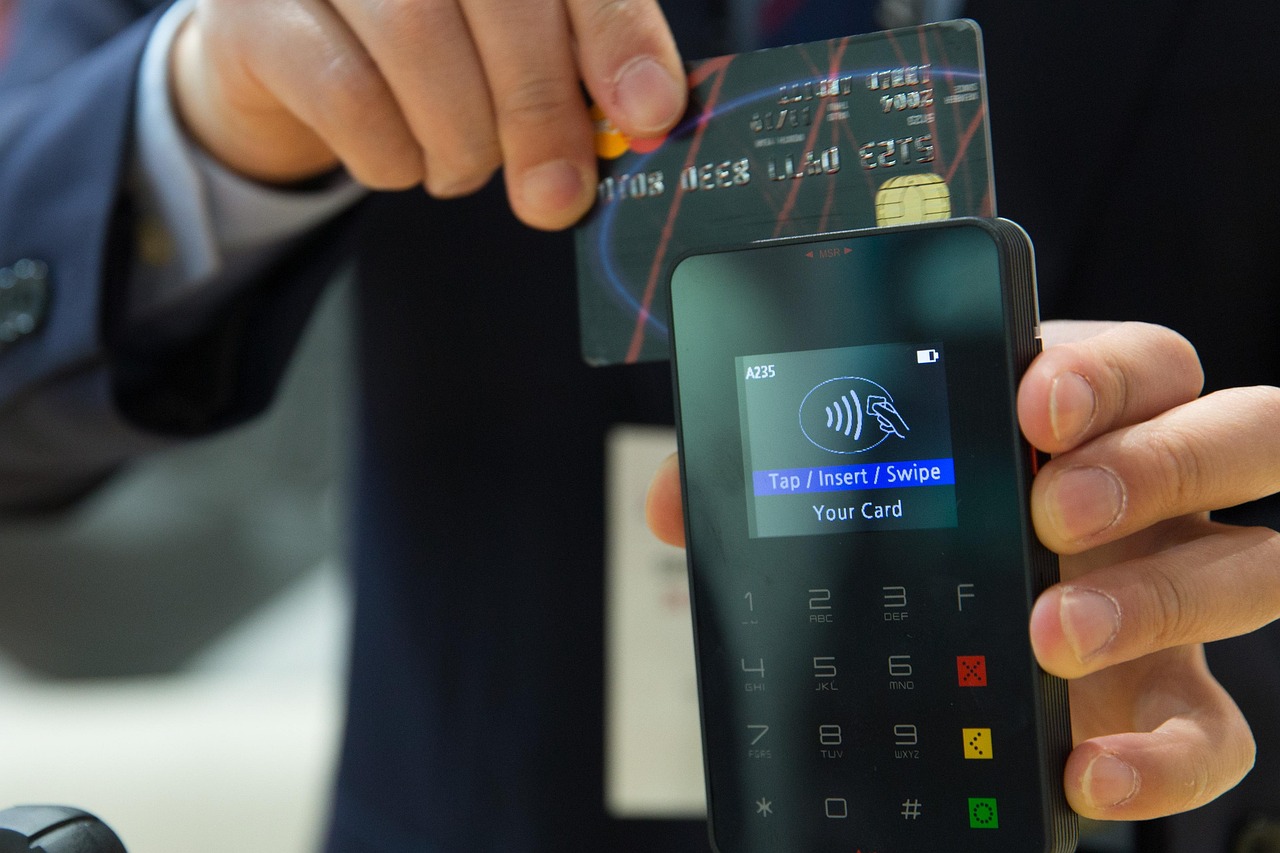
Choosing the right card payment machine is one of the most consequential operational decisions a UK retailer can make. Get it right and you reduce friction at the till, capture every sale, and gain meaningful data about your business; get it wrong and you face excessive fees, unreliable connectivity, and a customer experience that costs you repeat trade. This guide — written by the EPOS Direct UK team, who work with independent and multi-site retailers across the United Kingdom every day — covers everything from hardware types and integration options to honest cost expectations and how to get set up quickly.
Why Reliable Card Payment Acceptance Has Become Non-Negotiable for UK Retailers
Cash use in UK retail has declined sharply over the past decade, and the trend shows no sign of reversing. UK Finance publishes annual Payment Markets reports confirming that debit card payments now account for the majority of consumer transactions, with contactless accounting for a growing share of those. For a physical retailer, that means a card terminal is no longer optional infrastructure — it is as fundamental as the lights staying on.
Beyond simply accepting payment, a well-chosen card machine shapes the customer experience at its most critical moment. Speed, reliability, and the ability to accept Apple Pay, Google Pay, and contactless cards without friction directly influence whether a customer returns. Equally important is what happens after the transaction: modern integrated systems feed payment data directly into your stock, reporting, and accounting — eliminating the double-keying and end-of-day reconciliation headaches that older, standalone terminals create.
Types of Card Payment Machines Available for Retail Shops
Not all card terminals suit every retail environment. Understanding the practical differences saves you from buying hardware that doesn't fit how your shop actually operates.
Countertop (Fixed) Terminals
Countertop terminals connect via Ethernet or broadband and are designed for a fixed till point. They offer the most stable connection, tend to be the lowest-cost hardware option, and are ideal for retailers with a dedicated checkout counter — think newsagents, off-licences, or boutique clothing shops with a single till position. The limitation is obvious: the machine doesn't move, so the customer must come to it.
Portable (Wireless) Terminals
Portable terminals use Wi-Fi or Bluetooth to communicate with a base unit and are well suited to shops where staff may need to take payment on the shop floor, in a fitting room, or at a market stall adjacent to a permanent location. Battery life and wireless range are the critical specs to evaluate. Our guide to the best wireless card machines for small businesses in the UK explores specific hardware options in detail.
Mobile (SIM-Based) Terminals
Mobile terminals operate over a 4G or 5G data connection, making them genuinely untethered. They suit market traders, pop-up retailers, delivery operations, or any business that operates away from a fixed broadband connection. Data costs and roaming limitations are worth reviewing before committing to a SIM-based device if your business crosses borders at trade fairs or events.
EPOS-Integrated Payment Devices
Integrated payment devices are not standalone card machines but components of a unified EPOS system. The payment terminal communicates directly with the till software, so the sale amount passes automatically without manual keying, and the completed transaction updates stock levels, customer records, and financial reports in real time. This is the category that most growing retailers should be aiming for, and it is explored in depth in our guide to card machine and till system combined solutions for UK businesses.
Key Features to Look For in a Retail Card Terminal
- Contactless & mobile wallet acceptance: Visa, Mastercard, Amex contactless, Apple Pay, and Google Pay should all be supported as standard. Check explicitly — not all acquirers enable every scheme by default.
- Transaction speed: A slow terminal creates queues. Look for sub-three-second approval times and fast receipt printing or digital receipt options.
- Connectivity redundancy: Even countertop terminals benefit from a 4G failover so a broadband outage doesn't bring your shop to a standstill.
- Screen size and readability: Customer-facing screens for PIN entry need to be legible; larger screens reduce miskey errors and speed up the queue.
- Integration capability: Does the terminal connect natively with your EPOS software via a certified integration, or does it rely on a manual semi-integrated workaround? Native integration is materially more reliable.
- PCI DSS compliance: All card payment hardware sold in the UK must be compliant with the Payment Card Industry Data Security Standard. Verify that any device you consider is on the PCI SSC's list of approved PTS devices — details are published at pcisecuritystandards.org.
- Reporting and settlement: Next-day settlement is now common; same-day settlement is available from some providers. Consider how settlement timing interacts with your cash flow.
How Card Payment Machines Integrate with Your EPOS Till System
This is the question that separates a merely functional setup from a genuinely efficient one. A standalone card machine accepts payments but creates two disconnected data streams — your till records one version of a sale, your payment provider records another, and your accounts team reconcile the gap at month end. Integration eliminates that gap entirely.
In a properly integrated system, the EPOS software sends the basket total to the payment terminal electronically. The customer pays; the terminal returns an approved or declined status. The EPOS software then closes the transaction, updates stock in real time, and logs the payment method against the sale record. No manual input. No discrepancy risk.
The practical result: faster transaction times, fewer errors, cleaner management reporting, and a significantly simpler end-of-day reconciliation. For retailers considering this upgrade — particularly those moving from a legacy cash register — our guide on switching from a cash register to a modern EPOS system covers the transition process in practical detail.
To see how integrated card payments work within a live retail environment, you can request a retail EPOS software demo and walk through the payment flow with a member of our team.
What "Integration" Actually Requires
- Your payment terminal must be certified to communicate with your EPOS platform — ask your provider for a list of certified acquirer partners.
- Your acquirer (the bank or payment processor behind your terminal) must support the integration protocol used by your EPOS software.
- The integration should be tested end-to-end before go-live; a demo environment is invaluable here.
Our article comparing the best EPOS systems with integrated card payments in the UK benchmarks the leading options across these criteria.
Understanding Costs: What UK Retailers Typically Pay
Costs vary considerably depending on transaction volume, average basket size, contract structure, and whether you opt for a bundled or separate hardware-and-acquiring arrangement. The figures below are honest indicative ranges for the UK market — not quotes, and not competitor pricing.
| Cost Component | Typical Range (UK Market) | Key Variables |
|---|---|---|
| Card terminal hardware (purchase) | Typically from £150 to £600+ per device | Basic countertop vs. smart integrated terminal |
| Card terminal hardware (rental/lease) | Often from £15 to £50+ per month per device | Contract length, provider, included support |
| Transaction fees (consumer debit) | Approximately 0.2%–1.75% per transaction | Interchange-plus vs. blended pricing, volume |
| Transaction fees (consumer credit) | Approximately 0.3%–2.5% per transaction | Card type (Visa/MC vs. Amex), pricing model |
| Monthly EPOS software subscription | Typically from £30 to £150+ per month per site | Feature tier, number of tills, add-ons |
| Full integrated retail EPOS setup | Most setups fall between £500 and £2,500+ upfront, or monthly from £50–£200+ | Hardware bundle, software tier, contract structure |
The "Which Pricing Model Is Right for Me?" Question
Blended-rate pricing (a single flat percentage per transaction, regardless of card type) is simpler to budget but often more expensive for high-volume retailers whose customers predominantly use debit cards. Interchange-plus (or "cost-plus") pricing passes through the card scheme's own interchange rate plus a fixed processor margin, which is more transparent and typically better value once your monthly turnover exceeds a meaningful threshold. Ask any acquirer to show you both models applied to your actual sales data before committing.
On the EPOS software side, our article comparing monthly EPOS subscriptions versus outright purchase works through the real financial maths behind each model so you can make an evidence-based decision rather than a gut-feel one.
Selecting a Card Payment Provider: What UK Retailers Should Compare
The UK market offers a broad range of payment acquirers and aggregators — from established banks and specialist merchant service providers to newer fintech-style processors. Rather than ranking competitors (whose pricing and terms change frequently), the most reliable approach is to evaluate any provider against a consistent framework.
| Evaluation Criterion | What to Ask | Why It Matters |
|---|---|---|
| Settlement speed | Is next-day settlement standard? Is same-day available? | Directly affects your working capital and cash flow management |
| Contract length & exit terms | Is it rolling monthly or a fixed term? What are early-exit fees? | Avoids being locked into a poor rate as your volume grows |
| EPOS integration compatibility | Is this acquirer certified with your specific EPOS platform? | Non-certified integrations introduce error risk and slower support |
| Chargeback handling | What is the process and typical resolution time? | Chargebacks are a real operational risk, especially in fashion and gifts retail |
| Customer support | Is support 24/7? Is it UK-based? What is the average response time? | A terminal down on a Saturday afternoon needs an answer in minutes, not days |
| Multi-location support | Can you manage multiple merchant IDs under one account? | Critical for retailers planning to expand beyond a single site |
For a direct comparison of how EPOS Direct's integrated approach stacks up against alternatives in the wider market, see our complete 2026 guide to EPOS Direct versus competitor till systems.
How to Get Set Up with a Card Machine and EPOS System Through EPOS Direct
EPOS Direct offers UK retailers a unified route to both hardware and integrated payment acceptance, meaning you deal with a single point of contact for your till system, software, and card terminal rather than managing separate vendor relationships. This matters more than it might appear: when something goes wrong at 9am on a busy trading day, knowing exactly who to call — and having that person able to see your entire setup — resolves problems far faster than navigating between three different support lines.
The Typical Setup Journey
- Discovery call: A member of the EPOS Direct team reviews your shop type, transaction volume, number of till points, and any existing software or hardware you want to retain. You can talk to an expert online to start this conversation without commitment.
- System recommendation: Based on your requirements, a hardware and software bundle is proposed — including which payment terminal is certified for native integration with your chosen EPOS software tier.
- Demo: Before you commit, you can walk through the actual retail software in a live environment. Request a free demo to see the complete payment and till workflow in action.
- Commercial agreement: EPOS Direct outlines hardware costs (purchase or subscription), software fees, and any acquiring arrangements clearly, so there are no surprises after go-live.
- Installation and training: Hardware is configured and installed; staff training is included to ensure your team is confident on day one.
- Ongoing support: UK-based support covers both the EPOS software and the integrated terminal, so you have a single escalation path.
For retailers ready to explore current packages, our retail EPOS offers page details available hardware and software bundles. You can also visit the EPOS Direct UK home page for the full range of offers and information across all retail and hospitality categories.
If you prefer to discuss your requirements before looking at specific packages, request a call back and a specialist will be in touch at a time that suits you.
The Short Answer: What UK Retailers Actually Need to Know
For any UK retail business taking payments in person, a card payment machine that integrates directly with your till software is the configuration that delivers the best combination of customer experience, operational accuracy, and useful reporting data. Standalone terminals are cheaper upfront but create reconciliation work and data gaps that cost you more in time and insight than the hardware saving justifies. The right integrated setup — matched to your transaction volume and chosen through a provider who can support both the till and the terminal — pays for itself in efficiency within a typical trading year.
Next Steps for UK Retailers
Whether you are setting up your first retail till or replacing an ageing system that has outgrown your business, EPOS Direct UK has worked with independent retailers, regional chains, and specialist stores across the country to find configurations that genuinely fit — not just hardware that ships quickly. Our retail specialists understand the specific pressures of UK shop environments: seasonal peaks, multi-SKU stock management, and the expectation of fast, seamless checkout.
Start by exploring our practical buyer's guide to the best till systems for small businesses, or go straight to a live conversation: talk to an EPOS Direct expert online today and get a system recommendation built around your shop, your volume, and your ambitions.
Frequently asked questions
- What is the typical cost of a card payment machine for a retail shop in the UK?
- Costs vary depending on the type and provider. Countertop card terminals typically cost between £150 and £350 to buy outright, while portable and wireless models range from £200 to £500. Some providers offer terminals free on a contract with monthly fees of £15 to £40. Transaction fees in the UK generally run between 0.75% and 1.75% per card payment, depending on your sales volume and provider. Integrated EPOS and payment bundles from providers like EPOS Direct can offer better value by combining hardware and software in one package.
- Do I need a separate card machine if I already have an EPOS till system?
- Not necessarily. Many modern EPOS systems, including those from EPOS Direct, support integrated payment terminals that communicate directly with your till. This means transactions are automatically recorded, reducing manual entry errors and speeding up the checkout process. If your current card machine is standalone, it may be worth upgrading to an integrated solution for a smoother retail operation.
- Which card payment methods should my retail terminal support in 2024?
- At a minimum, your card machine should accept chip and PIN, contactless payments up to £100, and mobile wallets such as Apple Pay and Google Pay. For higher-volume or specialist retail environments, look for terminals that also support gift cards, loyalty schemes and multi-currency if you serve international customers. Most reputable UK providers now include all of these as standard.
