We use cookies to make your experience better.
To comply with the new e-Privacy directive, you agree to the privacy policy and our use of cookies

Do Card Payment Machines Need a Phone Line? What UK Businesses Should Know
Do Card Payment Machines Need a Phone Line in the UK?
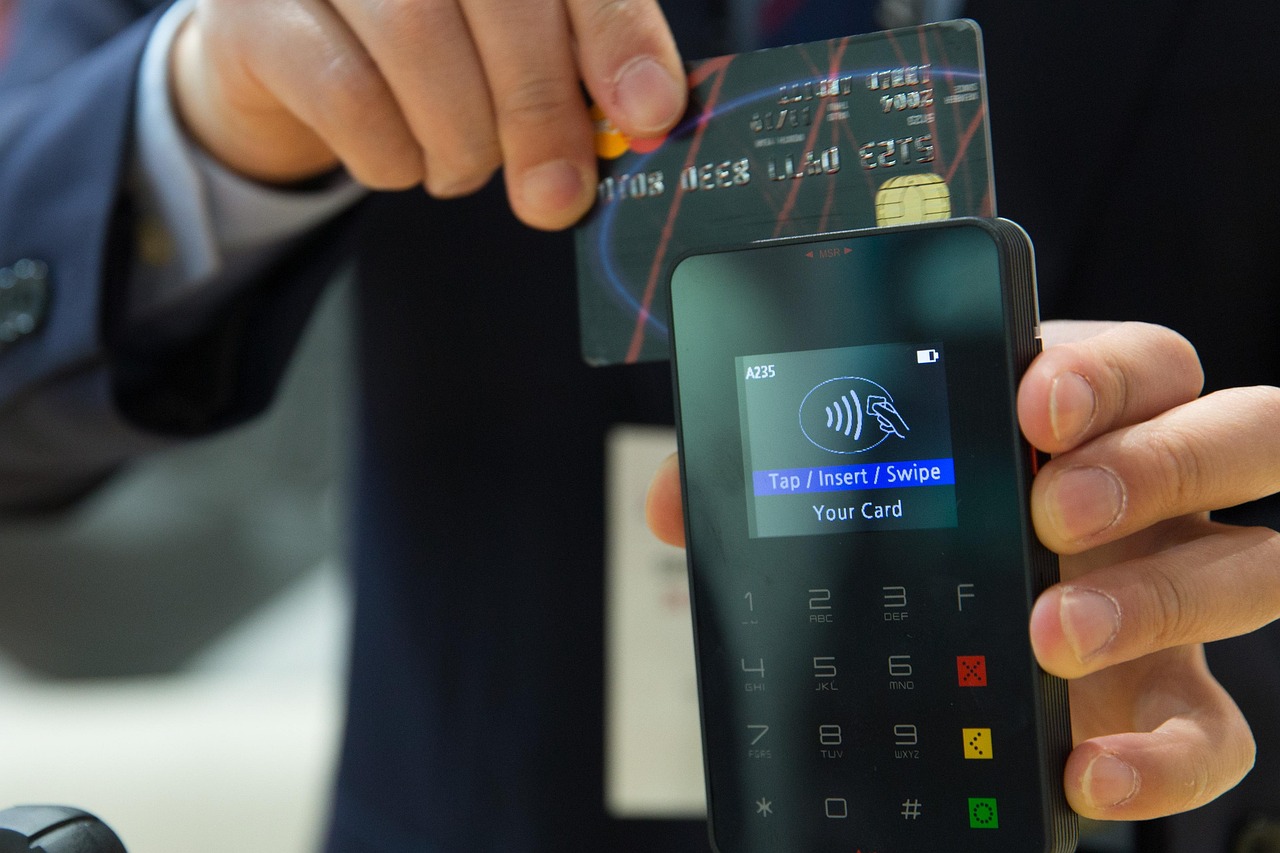
The short answer is no — the vast majority of modern card payment machines used across the UK no longer require a traditional phone line to process transactions. Today's terminals connect via broadband, Wi-Fi, or mobile data (4G/5G), giving businesses far greater flexibility in where and how they take payments. Understanding which connection method suits your operation, and what to do if that connection fails, is what separates a resilient payment setup from an unreliable one.
How Card Payment Machines Connect: A Quick Overview
Card payment technology has evolved considerably since the era of dial-up terminals and dedicated PSTN (Public Switched Telephone Network) lines. Early chip-and-PIN machines dialled out over a standard phone line each time a transaction was processed — a process that was slow, tied to a fixed location, and increasingly impractical for modern businesses. Today, that dial-up connection has been almost entirely replaced by internet-based and mobile data protocols that are faster, more reliable, and far more versatile.
Most terminals now communicate with payment processors using encrypted internet connections, whether through a router at your premises or a built-in SIM card. The transaction journey — from card tap to approved receipt — typically completes in a matter of seconds, regardless of which connection type is used.
Do Modern Card Readers Still Require a Traditional Phone Line?
For the overwhelming majority of UK businesses acquiring a card machine today, a PSTN phone line is simply not a requirement. BT Openreach's ongoing shift away from the copper telephone network (a programme progressing across the UK infrastructure estate) has accelerated the retirement of analogue-dependent terminals. Providers have moved decisively to IP-based and SIM-based connectivity.
There are narrow legacy scenarios — typically older countertop terminals still in service at some small retailers or hospitality venues — where a terminal may still be configured to fall back to a phone line. However, any new terminal issued in the UK market today will connect via broadband or mobile data as standard.
The definitive answer for buyers: if you are sourcing a new card payment machine or an integrated EPOS solution in 2025–2026, you do not need a phone line. You need a stable internet connection, a Wi-Fi network, or a mobile data signal — and ideally a contingency plan if your primary connection drops.
The Four Main Connection Types for UK Card Machines
1. Broadband (Ethernet / Fixed Internet)
A wired broadband connection — where the terminal connects directly to your router via an Ethernet cable — remains the gold standard for countertop terminals in fixed retail and hospitality environments. It is consistent, low-latency, and not susceptible to wireless interference. For busy checkout environments processing high transaction volumes, this is typically the most dependable option.
2. Wi-Fi
Wi-Fi-connected terminals offer the flexibility of a wired setup without the physical cable constraint. They are particularly well-suited to table-side payment in restaurants, roaming sales floors in retail, and any counter configuration where running a cable is impractical. The key consideration is router coverage and network stability — a weak Wi-Fi signal in a busy kitchen or a crowded trade show venue can introduce latency or disconnections.
3. 4G / 5G Mobile Data (Built-in SIM)
Terminals with an integrated SIM card connect over the mobile data network and are entirely independent of your premises' broadband or Wi-Fi. This makes them ideal for market traders, mobile beauticians, delivery drivers, pop-up retail, outdoor events, and any business that moves. As 5G coverage continues to expand across UK urban and suburban areas, these terminals are becoming faster and more capable by the month.
4. PSTN (Legacy Phone Line)
Traditional dial-up over a copper phone line is effectively obsolete for new deployments. It is worth being aware of as a legacy concept — and as context for why older contracts may have included a phone line rental requirement — but no reputable provider will recommend or supply a PSTN-only terminal for a business setting up today.
Connection Types at a Glance: Comparison Table
| Connection Type | Best For | Speed | Mobility | Reliability Risk |
|---|---|---|---|---|
| Broadband (Ethernet) | Fixed countertop retail & hospitality | Fast | None — fixed location | Low (if ISP is stable) |
| Wi-Fi | Table-service restaurants, sales floors | Fast to moderate | High — within range | Moderate (interference, router issues) |
| 4G / 5G SIM | Mobile, market, pop-up, delivery | Fast (5G) to moderate (4G) | Full — anywhere with signal | Low to moderate (coverage dependent) |
| PSTN (Dial-up) | Legacy terminals only — not recommended | Slow | None | High — network being retired |
Which Connection Method Is Best for Your Business Type?
The right connectivity approach depends on your physical environment, transaction volume, and how your staff move around the sales space. Here is a practical breakdown:
- Independent retailers with a fixed till point: A wired broadband connection integrated into a full EPOS setup is typically the most robust choice. If you are planning a modern setup, our guide to the best till systems for small shops covers how hardware and payments come together.
- Cafés, restaurants, and quick-service venues: Wi-Fi-connected or SIM-enabled handheld terminals allow staff to take payment at the table, reducing queue times and improving the dining experience. Explore our hospitality and restaurant EPOS offers to see how integrated card payments work in a full system context.
- Market traders, mobile therapists, tradespeople: A 4G/5G SIM-based reader is the only practical option. You have no fixed broadband to rely on, so built-in mobile data is essential. Our guide to the best wireless card machines for small businesses provides a detailed look at the available options.
- Multi-site and growing retailers: Businesses operating across several locations benefit most from a centralised cloud EPOS system with integrated card payments — ensuring consistent data, consolidated reporting, and the flexibility to use different connection types site by site.
What Happens to Your Payments If Your Internet Goes Down?
This is one of the most practical questions any business owner should ask before committing to a card payment setup. A dropped internet connection at the wrong moment — peak Saturday trading, a busy Friday evening service — can bring sales to a halt if your system has no contingency.
Modern EPOS-integrated terminals handle this in several ways:
- Offline transaction queuing: Some terminals can store a limited number of approved transactions locally and transmit them once connectivity is restored. This carries a degree of chargeback risk and is subject to your payment provider's terms.
- Automatic SIM failover: Higher-specification setups can switch automatically from broadband to a mobile data connection if the primary connection drops — effectively invisible to staff and customers.
- Dual-SIM or multi-network terminals: Certain enterprise-grade terminals connect across multiple mobile networks, so a single network outage does not interrupt trading.
- Maintaining a backup device: Many businesses simply keep a standalone 4G card reader as a contingency — a low-cost insurance policy against broadband failures.
If resilience matters to your business (and for most, it should), discuss failover options explicitly when specifying your setup. You can talk to an expert online at EPOS Direct UK to get connectivity advice tailored to your specific trading environment.
What Does a Card Payment Machine Setup Cost in the UK?
Costs vary depending on whether you are acquiring a standalone reader or an integrated EPOS solution with card payments built in. As a general guide based on current UK market conditions:
- Standalone card readers (SIM or Wi-Fi): Typically from around £20–£50 for entry-level devices on a pay-as-you-go basis, with transaction fees typically ranging from approximately 1.5% to 2.5% per transaction depending on card type and provider.
- Countertop terminals on a merchant services contract: Often supplied at low or no hardware cost, with monthly service fees typically ranging from around £15 to £40 per terminal, plus a negotiated transaction rate.
- Integrated EPOS systems with card payments: Most full setups — including hardware, software, and integrated payment processing — fall in a range of approximately £30 to £100+ per month on a subscription model, depending on features, number of terminals, and support level. For a deeper look at the cost trade-offs, our article on monthly EPOS subscriptions versus outright purchase is worth reading before you commit.
These figures are indicative only — your actual costs will depend on transaction volumes, hardware choices, and the specific terms agreed with your provider. Always request itemised pricing and clarify what is included in any quoted monthly fee.
How Card Machine Connectivity Fits Into a Full EPOS System
For most established businesses, a standalone card reader is a starting point rather than an end destination. Integrating card payments directly into an EPOS system — so that the till, the payment terminal, and your back-office reporting all communicate with one another — eliminates manual reconciliation, reduces human error, and gives you real-time visibility of sales data.
In an integrated setup, the connection requirements are unified: your EPOS system connects to your network, and the card terminal communicates through the same infrastructure. This means a single reliable broadband or Wi-Fi connection supports your entire point-of-sale environment, with the option of a SIM failover layer for critical resilience.
If you are considering moving from a basic card reader to a full system, our guide to EPOS systems with integrated card payments covers the key considerations in detail. Businesses currently on a traditional cash register should also read our guide on upgrading from a cash register to a modern EPOS system — the connectivity and card payment questions covered here are directly relevant to that transition.
To explore what a fully integrated setup looks like in practice, you can request a free demo and see the system working end to end before making any commitment. For retail businesses in particular, our retail EPOS offers page is a good starting point for scoping hardware and payment options together.
More information on available systems, current offers, and the full product range is available on the EPOS Direct UK home page.
Choosing the Right Card Payment Setup for Your UK Business
A few clear decision criteria to carry into any conversation with a provider:
- Where will you trade? Fixed premises favour wired broadband or Wi-Fi; mobile or outdoor trading demands a SIM-enabled device.
- How many terminals do you need? Multi-terminal environments benefit significantly from integrated EPOS rather than a fleet of unconnected readers.
- What is your contingency if your primary connection fails? Make sure failover capability is explicitly addressed — not assumed.
- How do you want to own the hardware? Outright purchase versus subscription affects both upfront cost and long-term flexibility.
- What data do you need from your payments? Integrated systems provide sales analytics, stock insights, and reconciliation that standalone readers cannot.
In Summary
Card payment machines in the UK no longer need a phone line — and for any new setup, the question is simply which internet or mobile data connection best fits your business model. Whether you need a compact wireless reader for a market stall or a fully integrated EPOS solution across multiple retail sites, the connectivity options available today are more reliable, more flexible, and more capable than anything the old dial-up era could offer.
The EPOS Direct UK team works with businesses across retail, hospitality, and specialist sectors every day to design payment and EPOS setups that are practical, resilient, and cost-effective. If you would like guidance on which connection method and terminal type is right for your specific situation, request a call back and speak with a specialist who understands the full picture.
Written by the EPOS Direct UK team, who support businesses across the United Kingdom with EPOS and payment technology every day.
Frequently asked questions
- Can I use a card machine in my shop if I only have a broadband connection and no phone line?
- Yes, absolutely. The vast majority of modern card payment machines in the UK connect via broadband (Ethernet or Wi-Fi), 4G, or 5G — they do not require a traditional analogue phone line at all. In fact, Openreach's PSTN switch-off, scheduled for completion by January 2027, means older dial-up card terminals are already being phased out across the UK. If you currently rely on a phone line for your card machine, now is a good time to migrate to a broadband or mobile-data solution.
- How much does a card payment machine typically cost for a small UK business?
- Costs vary depending on the type and contract. Standalone portable card readers from providers like SumUp or Square start from around £19–£49 as a one-off purchase, with transaction fees of 1.69%–2.5%. Integrated card terminals that connect to a full EPOS system typically cost £150–£400 per terminal, often available on monthly rental agreements from around £15–£30 per month. When factoring in transaction rates negotiated through a merchant services provider, integrated EPOS setups often deliver a lower total cost for businesses processing more than £5,000 per month.
- What should I do if my internet drops — will I still be able to take card payments?
- It depends on your terminal and provider. Some card machines offer an offline or 'store and forward' mode that queues transactions locally and submits them once connectivity is restored — though this carries a small risk of declined cards not being caught in real time. A more reliable backup is choosing a card terminal with dual connectivity, such as one that switches automatically between Wi-Fi and 4G. When integrated with an EPOS system, many setups also allow cash transactions to continue seamlessly during an outage, keeping your business running without interruption.
