We use cookies to make your experience better.
To comply with the new e-Privacy directive, you agree to the privacy policy and our use of cookies

How Card Machines Connect to a Till System: A Complete Guide for UK Businesses
How Card Machines Connect to a Till System: Everything UK Retailers and Hospitality Businesses Need to Know
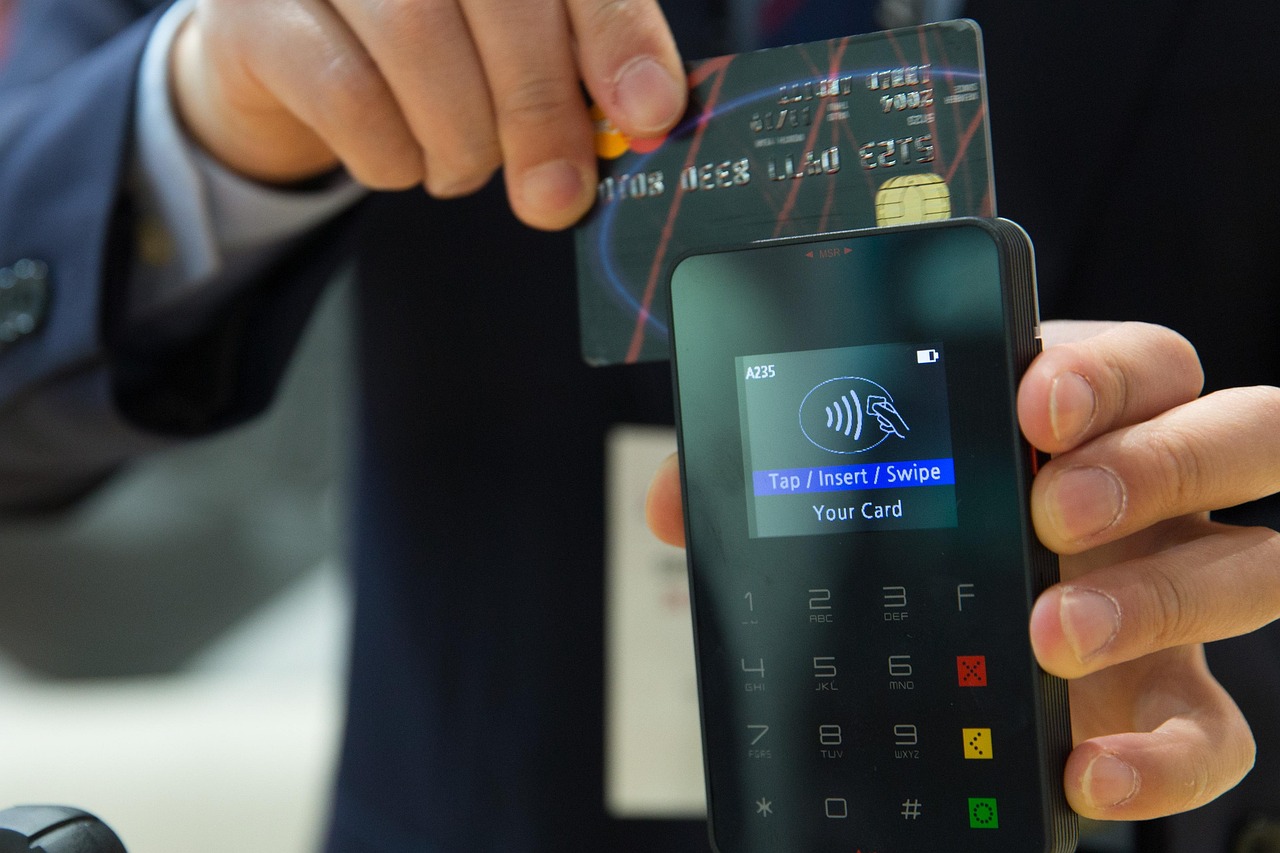
A card machine connects to a till system either as a standalone device that operates independently, or as an integrated terminal that communicates directly with the EPOS software — automatically posting transaction totals, eliminating manual entry errors and speeding up the checkout experience. For UK retailers and hospitality businesses, understanding the difference between these two approaches, and the physical or wireless methods used to link them, is essential before investing in any point-of-sale setup. Whether you run a boutique shop, a busy restaurant or a pharmacy, the connection method you choose will shape everything from queue speed to end-of-day reconciliation.
Standalone Card Machines Versus Integrated Payment Terminals
The first distinction every business owner needs to understand is whether their card reader is connected to their till at all — or simply sitting beside it as a separate device.
Standalone card machines
A standalone terminal processes payments independently. The cashier reads the total from the till screen, keys the amount manually into the card machine, and the customer taps, inserts or swipes their card. The payment is processed by the card machine's own connection (mobile data or Wi-Fi), and the till records the sale separately. There is no electronic handshake between the two devices.
This setup is inexpensive to start but creates real operational problems: keying errors inflate or undercharge transactions; reconciliation is manual and time-consuming; and reporting across the two systems rarely aligns cleanly without significant staff effort.
Integrated payment terminals
An integrated terminal receives the basket total directly from the EPOS software. When the cashier presses "Pay by card", the till sends the exact amount to the terminal electronically. The customer pays, the approval or decline is sent back to the till, and the sale is recorded — automatically and accurately — in one seamless flow. This is the architecture used by serious retail and hospitality operations, and it is the standard EPOS Direct UK recommends for any business processing more than a handful of card payments per day.
If you are exploring which system tier suits your business, our guide to the best till systems for small businesses in the UK walks through the full range of options.
How Card Machines Physically and Digitally Connect to a Till
Integration between a card terminal and a till system relies on one of two layers: a physical connection (a cable or local network port) or a digital/wireless connection (Wi-Fi, Bluetooth, or cellular). In practice, most modern integrated systems use a combination — for example, the terminal sits on an Ethernet-connected local network and the EPOS software sends payment requests over that network using a payment protocol called the Payment Application Programming Interface (Payment API) or, in older setups, a direct serial communication standard.
The payment processor or acquirer (Worldpay, Stripe Terminal, Dojo, Paymentsense, and others active in the UK market) provides drivers or an SDK that the EPOS software uses to "speak" to the terminal. This is why not every card machine works with every till — integration must be validated between the EPOS platform and the payment provider before it can function reliably.
The Four Main Connection Methods Explained
1. USB
A USB cable creates a direct, stable, point-to-point connection between the terminal and the till. It is typically used in fixed counter environments — traditional retail tills, pharmacy counters, service desks — where the terminal never needs to move. Setup is straightforward: the EPOS software recognises the device via a driver, and communication is fast and reliable. The limitation is obvious: the customer must come to the terminal, and the cable tethers the device to one position.
2. Ethernet (wired LAN)
Ethernet connects the card terminal to your local area network via a physical cable, usually through a network switch that also connects your till hardware. The EPOS software communicates with the terminal over the local network using a specific IP address assigned to the terminal. Ethernet is the most stable and secure connection method — it is immune to radio interference and does not compete for bandwidth with other wireless devices. It is the preferred choice for high-volume retail counters and restaurant service stations where reliability is non-negotiable.
3. Wi-Fi
Wi-Fi-enabled card terminals connect to your business network wirelessly and receive payment requests from the EPOS system over that same network. This allows limited portability within Wi-Fi coverage — useful in restaurants where a server brings the terminal to the table but the payment is still sent from the till system, or in large retail spaces with multiple tills sharing a single payment gateway. Network congestion, router placement and interference are real considerations; a dedicated business-grade Wi-Fi network is strongly advisable. For more on choosing a wireless-capable terminal, see our guide to the best wireless card machines for small businesses in the UK.
4. Bluetooth
Bluetooth integration is less common in fully integrated EPOS setups but appears in smaller or mobile configurations — for example, a tablet-based EPOS paired with a Bluetooth card reader at a market stall, pop-up or mobile service. The effective range is limited (typically under 10 metres in real-world conditions), and Bluetooth connections can be less stable than network-based ones in busy environments. That said, for low-volume or highly mobile operations, Bluetooth pairing offers the simplest hardware footprint.
Integrated vs Semi-Integrated Payments: Which Setup Suits Your Business?
Beyond the physical connection, there is an architectural choice between fully integrated and semi-integrated payment setups that affects security, compliance and flexibility.
- Fully integrated: Card data flows through the EPOS system, which communicates directly with the payment processor. Offers the richest feature set (loyalty, split bills, itemised receipts on the terminal) but places greater PCI DSS compliance obligations on the EPOS platform.
- Semi-integrated: The EPOS software sends only the payment amount to a secure, PCI-certified terminal. Sensitive card data never touches the EPOS system — it is handled entirely within the terminal's secure environment. This significantly reduces PCI DSS scope for the merchant and is increasingly the model preferred by UK acquirers and recommended by the Payment Card Industry Security Standards Council (PCI SSC — verify current guidance at pcisecuritystandards.org).
For most UK SMEs, a semi-integrated architecture with a certified terminal strikes the right balance between functionality and compliance simplicity. Our guide to the best EPOS systems with integrated card payments in the UK compares the leading options in detail.
What Happens at the Point of Sale When a Card Payment Is Made
Understanding the transaction flow demystifies most of the connection questions buyers ask. Here is what happens in a well-integrated setup:
- The cashier finalises the basket on the EPOS till and selects card payment.
- The EPOS software sends the exact total to the integrated terminal (via USB, Ethernet or Wi-Fi).
- The terminal prompts the customer to tap, insert or swipe their card.
- The terminal encrypts the card data and sends an authorisation request to the acquirer's payment gateway over its own secure internet connection (separate from the EPOS network traffic).
- The acquirer contacts the card scheme (Visa, Mastercard, Amex) and then the issuing bank, which approves or declines the transaction — typically within two to three seconds.
- The approval or decline is returned to the terminal, which displays the result and prints or sends a receipt.
- The terminal sends the result back to the EPOS software, which automatically marks the sale as paid and updates stock, sales reporting and end-of-day totals.
Steps 4 to 6 happen entirely within the payment network — the EPOS till simply waits for the result. This architecture is why the internet connection to the payment gateway (usually cellular 4G/5G on the terminal or broadband at the business) must be separate from, and independent of, any technical issues on the EPOS side.
Common Problems When Linking a Card Reader to a Till — and How to Fix Them
Even well-designed integrations encounter issues. The most frequent problems UK businesses report, and the practical fixes:
- Terminal not found by the EPOS software: Usually an IP address conflict or the terminal's IP has changed after a router restart. Assign the terminal a static (fixed) IP address in your router's DHCP settings.
- Amounts not transferring correctly: Check the currency and decimal settings in both the EPOS software and the terminal configuration. A mismatch causes the terminal to receive, for example, £1,250 instead of £12.50.
- Bluetooth drops mid-transaction: Interference from other devices or excessive distance. Move the terminal closer to the till hardware, and ensure no other Bluetooth devices are competing for the same channel.
- Slow approval times: The payment gateway connection is the bottleneck, not the till-to-terminal link. Check the terminal's cellular signal strength or, if using shared Wi-Fi, consider a dedicated SSID for payment terminals.
- End-of-day figures not reconciling: Often caused by voided or refunded transactions processed on the terminal but not reflected in the EPOS. Ensure refund workflows are completed through the EPOS interface, not by pressing buttons directly on the terminal.
If you are migrating from an older cash register setup, you may also find our guide on upgrading from a cash register to a modern EPOS system useful — it covers the common pitfalls of that transition in practical detail.
What Does an Integrated EPOS and Card Payment System Cost in the UK?
Costs vary significantly by business size, sector and chosen payment provider. The figures below are honest, indicative ranges based on the UK market — not quotes, and not competitor pricing.
| Setup Type | Typical Hardware Cost | Monthly Software & Support | Card Processing Rate (indicative) | Best For |
|---|---|---|---|---|
| Standalone card machine only | From approx. £50–£150 (rental or purchase) | None (no EPOS integration) | Typically 1.5%–2.5% per transaction | Very low volume; sole traders |
| Tablet EPOS + Bluetooth card reader | From approx. £300–£600 | Typically £20–£50/month | Typically 1.5%–2.0% | Mobile traders; pop-ups; small cafés |
| Counter EPOS + integrated terminal (Ethernet/USB) | From approx. £700–£1,500 per terminal | Typically £30–£80/month | Typically 0.8%–1.8% (negotiable by volume) | Retail shops; salons; pharmacies |
| Multi-terminal hospitality EPOS | From approx. £1,500–£4,000+ per site | Typically £60–£150/month per site | Typically 0.7%–1.5% (volume dependent) | Restaurants; pubs; hotels |
Processing rates are set by your acquirer, not your EPOS provider, and are always negotiable based on monthly turnover. If you are weighing up monthly subscription models against outright hardware purchase, our article on whether a monthly EPOS subscription is worth it lays out the financial comparison clearly.
Choosing a Fully Integrated EPOS and Card Payment System for Your UK Business
The right system depends on three practical factors: your trading environment (fixed counter vs. tableside vs. mobile), your transaction volume, and which payment providers your EPOS platform has certified integrations with. A system that looks attractive on paper but lacks a validated integration with your chosen acquirer will cause daily frustration.
Before committing, ask any EPOS provider the following:
- Which payment processors and acquirers do you have certified integrations with?
- Is the integration semi-integrated (PCI scope reduction) or fully integrated?
- What connection method does the integration use — USB, Ethernet or Wi-Fi — and is the terminal mobile-capable?
- What happens if the internet connection drops — can the terminal still process payments offline?
- Is integration support included in the monthly fee, or charged separately?
EPOS Direct UK builds and supports fully integrated EPOS and payment systems for retailers, restaurants, pharmacies and hospitality businesses across the UK. You can explore our EPOS software to see how payment integration is built into the platform, or book a retail EPOS software demo and a restaurant EPOS software demo to see the card payment flow live.
For sector-specific guidance on the right system for a shop environment, our resource on the best till systems for small shops covers selection criteria in detail. You can also browse EPOS Direct UK's full range of offers and information across retail and hospitality sectors.
Ready to Connect Your Card Machine Properly?
A poorly connected — or wholly disconnected — card machine costs UK businesses real money every day: in keying errors, reconciliation hours and missed reporting insight. Moving to a properly integrated EPOS and payment setup is one of the highest-return investments a growing business can make.
The EPOS Direct UK team works with independent retailers, restaurant groups, pharmacies and hospitality businesses across the UK every day to specify, install and support integrated payment systems. Request a free demo to see integration in action, talk to an expert online with any questions about connection methods, or request a call back and we will help you design a setup that fits your business from day one.
Written by the EPOS Direct UK team, who specify, install and support EPOS and integrated payment systems for businesses across the United Kingdom.
Frequently asked questions
- Can I use any card machine with my existing till system?
- Not always. Standalone card machines work independently but do not share data with your till, meaning staff must enter amounts twice. For true integration, your card terminal needs to be compatible with your EPOS software. Most modern EPOS providers, including EPOS Direct, supply pre-configured terminals that connect seamlessly via USB, Ethernet or Wi-Fi, eliminating manual re-keying errors.
- How much does a fully integrated card machine and EPOS till system cost in the UK?
- Costs vary by setup size and hardware choice. As a general guide, a single-terminal integrated EPOS system with a card reader typically starts from around £300–£600 for hardware, with monthly software licences ranging from approximately £20 to £60 per month. Payment processing fees in the UK usually sit between 0.5% and 1.75% per transaction depending on your provider and card volume. EPOS Direct offers tailored quotes, so it is worth contacting them directly for a package priced to your transaction levels.
- Does a card machine need a separate internet connection from the till?
- It depends on the connection type. When a card terminal connects via USB directly to the till, it can share the till's internet connection. Wi-Fi and Ethernet terminals typically connect to the same local network as the till rather than needing a separate line. Most modern card machines also have a 4G SIM as a backup so payments can continue even if your broadband drops, which is particularly useful for busy retail and hospitality environments.
